
Customer Case Study | Listerhill Credit Union
Facing an aging ATM fleet, Listerhill Credit Union modernized its branch and self-service experience through a core-connected ITM network, comprehensive member education, and a new approach to service delivery.
Listerhill at a Glance
- Year Founded: 1952
- $1.4B Assets
- 18 Branches
- 54 core-connected ITMs
- >$2 Savings per transaction
- 60%+ transactions moved to ITM/core
- 90%+ transactions completed through full self-service
- 54 to 1 ratio of ITMs to video tellers
Executive Summary
Listerhill Credit Union, based in Muscle Shoals, Alabama, began evaluating its self-service strategy in 2015 as its existing ATMs approached the end of life. Rather than simply replace the equipment, leadership explored interactive teller machines (ITMs) connected to the credit union’s core system. After evaluating available ITM options, Listerhill selected Hyosung, citing the core-connected functionality and self-service experience. The first four ITMs went live in February 2018. Listerhill supported the technology migration with hands-on member coaching and a shift from traditional teller roles to member-advocate roles. As of October 2026, the credit union reported 54 core-connected ITMs and one full-time plus one part-time ITM teller.
The Challenge
In 2015, Listerhill’s existing ATMs were nearing the end of life, creating a decision point for the credit union. Leadership could return to traditional ATMs, choose deposit-taking ATMs, or consider ITMs and core integration. The decision was not just about replacing hardware; it was about choosing a self-service model that could make routine transactions easierfor members while supporting the institution’s digital service direction.
Evaluating the Solution
To identify the right ITM partner, Listerhill Credit Union’s senior leadership team conducted extensive research and visited financial institutions across the country. While they were aware of Hyosung’s advanced self-service capabilities and seamless core integration, a visit to a financial institution located within a retirement community in Washington state proved especially influential. There, they observed members confidently using Hyosung’s core-connected ITMs and were impressed by how easily users adapted to the technology. The experience reinforced Listerhill’s confidence in Hyosung and ultimately helped shape the credit union’s ITM strategy.
Migration From Traditional ATM Service to Core-Connected ITMs
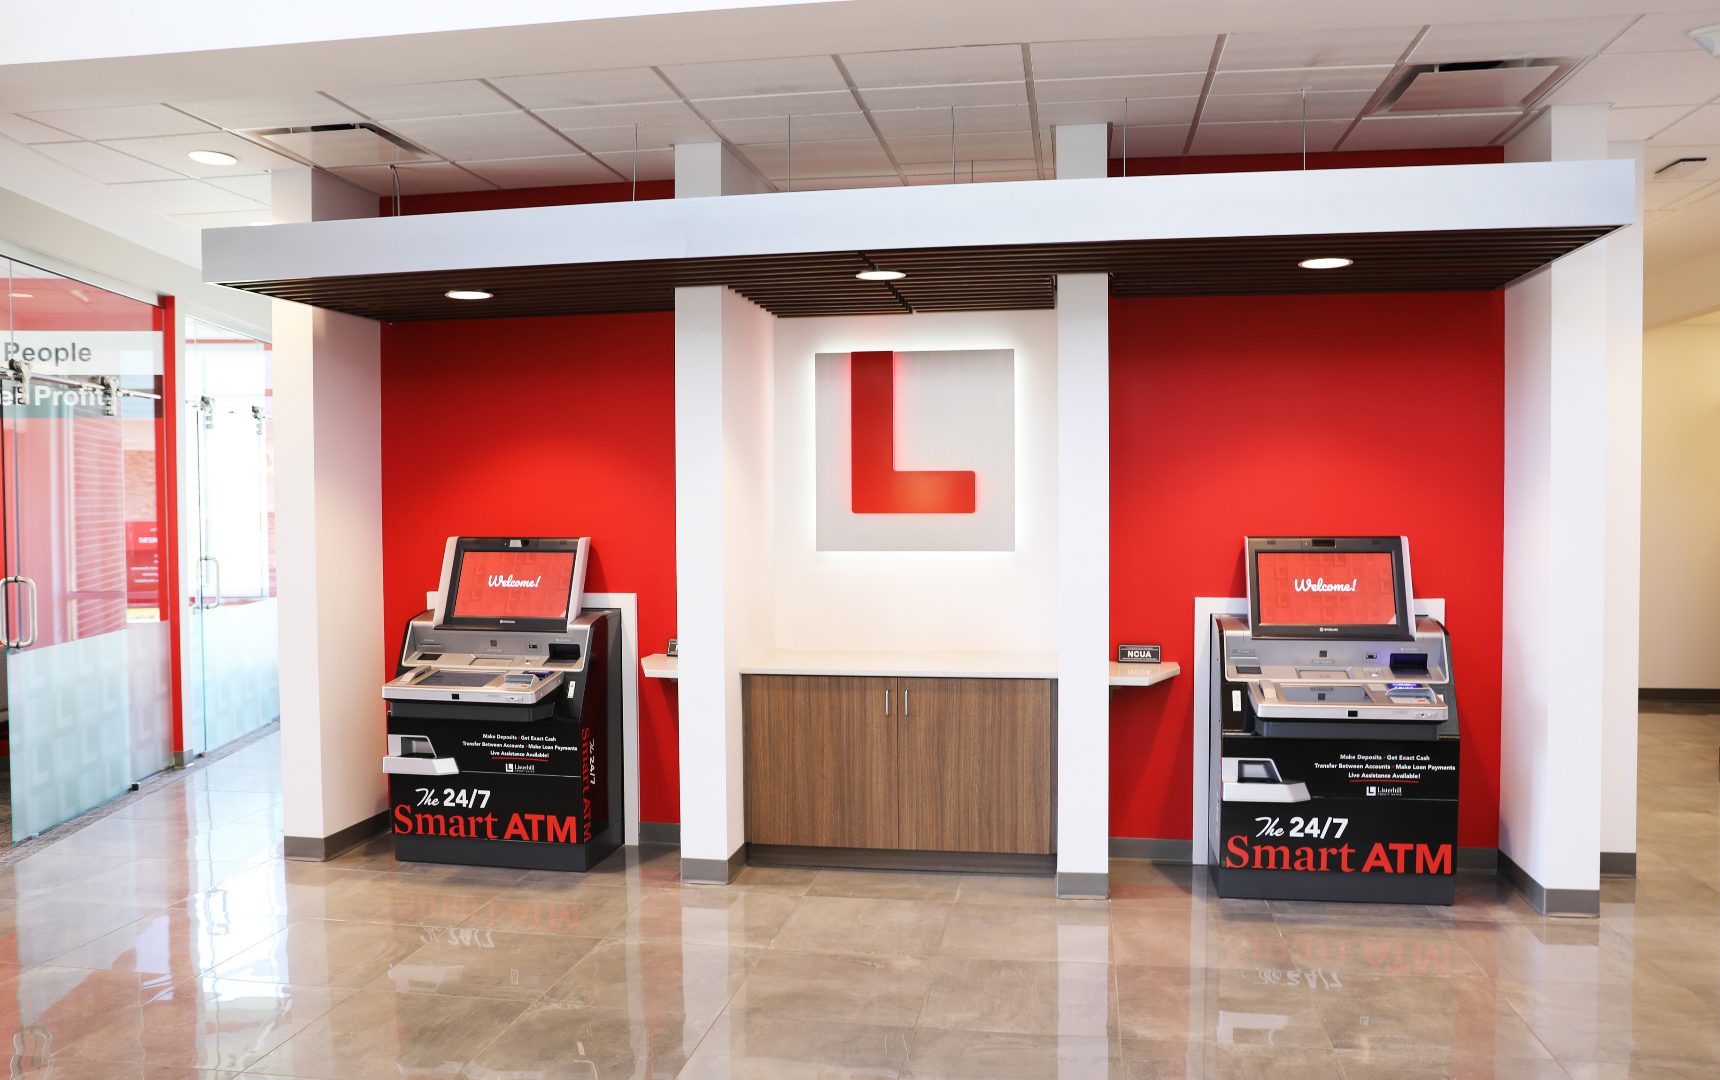
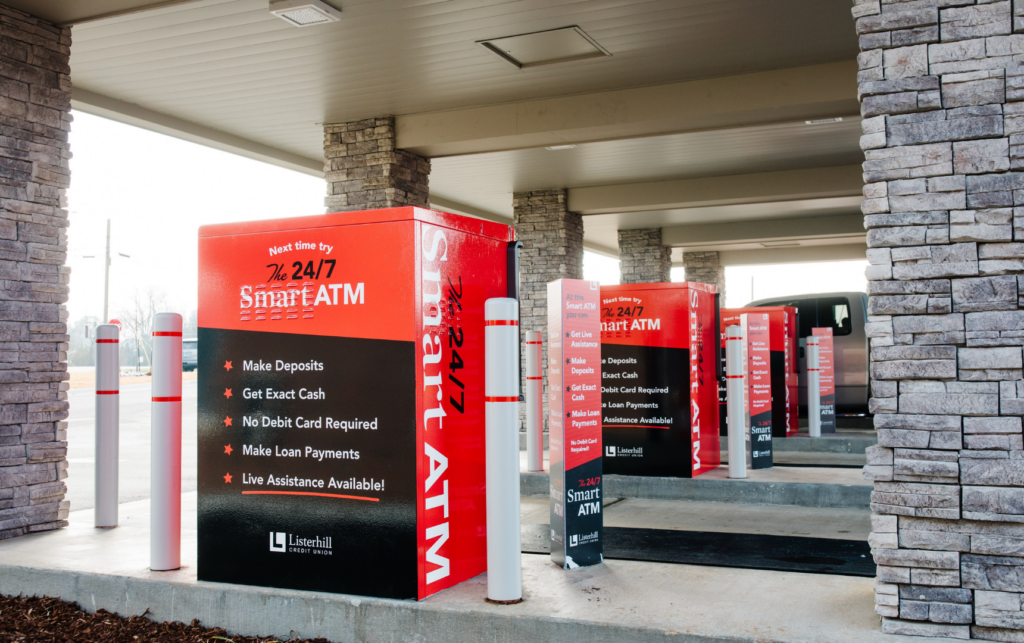
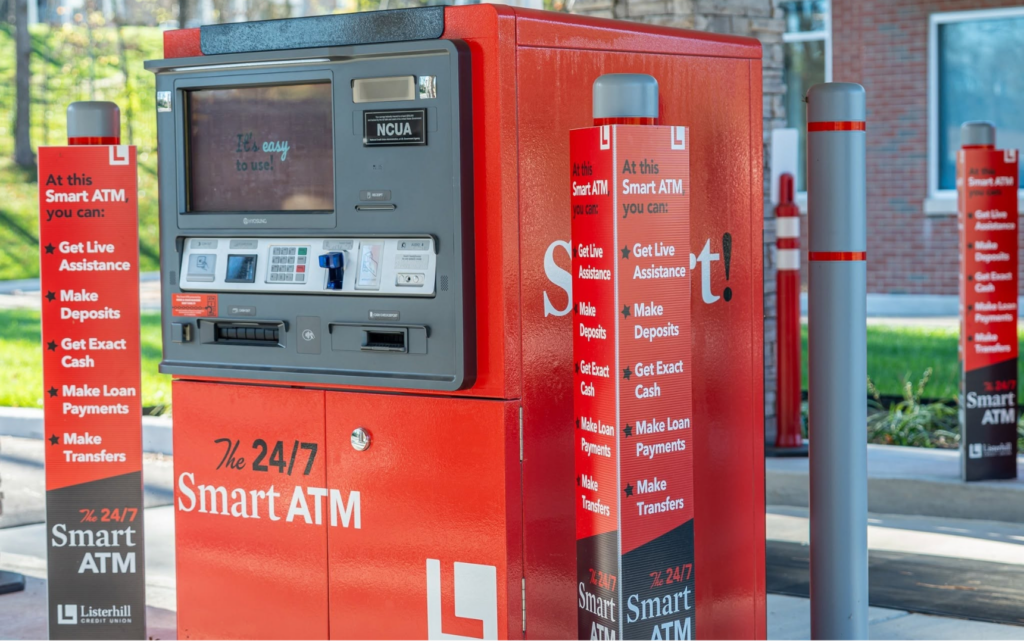
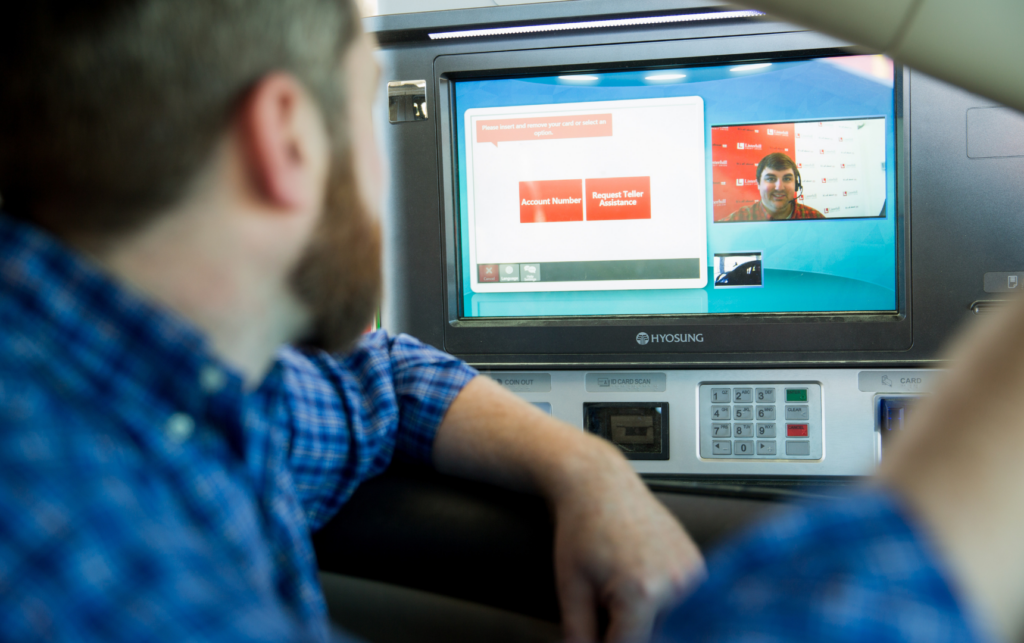
Listerhill launched its ITM strategy in February 2018 with an initial deployment of four machines, including three drive-through units and one lobby installation. The rollout provided members with a new, convenient way to complete routine transactions through a self-service experience with access to teller assistance when needed. Central to the initiative was Hyosung’s core integration, which enabled Listerhill to move beyond a traditional ATM replacement strategy and establish a more powerful and versatile service channel. Building on the success of the initial deployment, the credit union expanded its ITM network in phases, replacing legacy ATMs and drive-up vacuum tube systems at existing locations while incorporating ITMs into new branch designs. Today, Hyosung’s core-connected ITMs are deployed throughout Listerhill’s branch network, supporting a modernized approach to member service and branch operations.
Early Outcome: A Different Experience on a Traditionally Busy Day
Listerhill saw encouraging signs shortly after launch. Within the first month, they were expecting the third day of that month to be busy as usual; with branch members withdrawing cash and cashing checks. They recalled that the branch opened that day without its usual line, an unusual result that suggested members were already using the new ITM core channel.
Driving Member Adoption
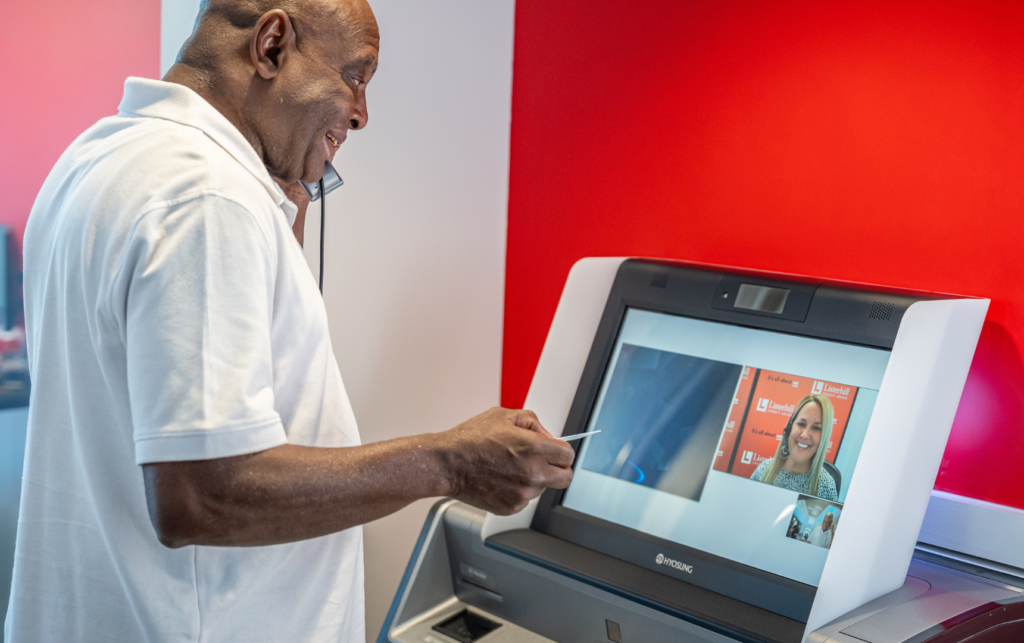
Listerhill treated adoption as a people-led change, not simply an equipment installation. At the first branch deployment, senior leaders and staff stood outside with members in cold winter weather and guided them through transactions at the ITMs. This provided support at the machine instead of sending inexperienced members to the ITM active teller and potentially creating a bottleneck. This approach proved highly successful in driving member adoption to the self-service ITM channel.
For subsequent deployments, staff used informal launch activities to encourage trial. In warmer weather, branches grilled hot dogs or hamburgers, and some locations handed members $5 bills to encourage them to try the new ITM core channel. The approach made the technology approachable and reinforced that help was available.
People and Process Change
Some employees initially had concerns about whether ITMs would affect job security. Listerhill responded by transitioning traditional teller roles into member-advocate positions, described as similar to universal banker roles. Employees could develop broader knowledge of the credit union and its products, creating opportunities for pay increases.
Operating at Scale
Listerhill is able to support its fleet of 54 core-connected ITMs with one full-time and one part-time ITM teller. The part-time employee helps on selected days when the full-time employee is off or during breaks. This staffing arrangement has been in place since the initial deployment, even as the ITM fleet has grown. Listerhill believes this is possible because of the self-service capabilities of the Hyosung solution.
When the COVID-19 pandemic disrupted lobby access, the credit union anticipated that additional ITM staffing might be needed and arranged for employees to be on standby. However, the extra staff ultimately were not needed. Listerhill attributes this to the solution’s ease of use and members’ familiarity with the self-service channel.
Institutional Savings
Listerhill has realized substantial operating cost savings through its deployment of Hyosung ITMs and core integration. The financial institution reports that more than 60% of teller transactions have migrated to the ITM core channel, while more than 90% of these transactions are completed through full self-service without ITM teller assistance. Listerhill calculates the cost of a traditional teller transaction at more than three dollars, while an ITM core transaction costs just over one dollar, saving the institution more than two dollars per migrated transaction. With roughly 988,824 ITM transactions annually, Listerhill calculates its annual savings at $1.2M.
Results at a Glance
- Annual network savings: Listerhill calculates annual operating cost savings of $1.2M fromtransaction migration
- Initial deployment: February 2018; four ITMs: three drive-through and one lobby.
- Network deployment: Listerhill focused on new branch builds and branch remodels, gradually deploying ITMs across its full branch network.
- Current network: 54 core-connected ITMs across the credit union’s 18 branches.
- Staffing reported at interview: One full-time and one part-time ITM teller.
- Early member experience: The credit union reported the usual line never formed on a traditionally busy day during the first month.
- Employee model: Traditional teller roles were transitioned toward member-advocator responsibilities.
- Pandemic readiness: Additional staff were placed on standby but were not ultimately required due to ease of self-service.
Lessons for Financial Institutions
- Use end-of-life replacement as a strategic decision point. Evaluate whether the next-generation channel should do more than replicate existing ATM functions.
- Evaluate the complete member experience. Leadership’s site visits helped them see how real members interacted with core-connected machines.
- Plan for adoption before launch. In-person guidance and approachable branch activities helped members try the new channel.
- Bring employees into the transition. Reframing teller work as member advocacy addressed job concerns and supported broader service capabilities.
- Track measurable migration outcomes. Transaction volumes, adoption rates, assisted-versus-self-service mix, uptime, and cost-to-serve would help quantify the impact.
Institution Profile
Listerhill Credit Union is headquartered in Muscle Shoals, Alabama, and was founded in 1952. At the time of the interview, it reported approximately $1.4 billion in assets, 18 branches, and 54 core-connected ITMs.